Showing posts with label accounts. Show all posts

Friday, August 2, 2019

What to know about required minimum distributions

If you’re taking money expert Clark Howard’s advice and diligently saving for retirement, you should know about required minimum distributions and how they could affect you later in life.

In this article, we’ll discuss what required minimum deductions are and what they could mean for you in your retirement years.

What are required minimum distributions?

Required minimum distributions (RMDs) are basically withdrawals that you are forced to take from your retirement accounts once you reach a certain age — typically 70 1/2, or when you retire if you work longer than that. Accounts that are affected by RMDs include:

  • 401(k) plans
  • Roth 401(k) plans
  • 403(b) plans
  • 457(b) plans
  • Profit-sharing plans
  • Individual Retirement Accounts (IRAs)
  • Simplified Employee Pension Individual Retirement Accounts (SEP IRAs)
  • Savings Incentive Match Plans for Employees (SIMPLE IRAs)

Roth IRAs, on the other hand, are not subject to required withdrawals until after the owner of the account dies.

When do you have to start taking your RMDs?

As mentioned, if you’re alive at age 70 1/2, that’s when you’re required to start taking your required minimum distributions.

However, you don’t have to withdraw the money immediately that day. You can wait to receive your first payment until April 1 of the year following when you turn 70 1/2.

Once you take your first distribution, you must take a distribution by December 31 of that year and every following year.

How do you figure out what your RMD will be?

Basically, the amount you must withdraw from your account each year is determined by a formula that considers how much money is in your account and divides that by the number of years the government thinks you have left to live. You can find those tables here.

Bankrate provides a pretty handy calculator that lets you see what your estimated required minimum distribution is both at present (if you’re already 70 1/2) and in the future.

We ran the numbers on someone who is currently 50 years old and has $300,000 in a retirement account with an average rate of return of 5% per year:

Advertisement

Required minimum distributions

As you can see, this person would be required to withdraw around $30,000 at 70 1/2. That number increases slightly each year until they are in their early 90s, if they are lucky enough to live that long.

What’s also interesting to note (in the graph on the bottom) is that the value of the retirement account never drops below $300,000, even if this person lives to be 100 years old.

What happens if you have more than one retirement account?

If you have more than one IRA, you must calculate the RMD on each individual account. However, you can withdraw the total of the RMDs from one or more of those accounts. You do not have to take the RMD from each account individually. This applies to multiple 403(b) accounts, as well.

RMDs from other types of retirement accounts like 401(k) and 457(b) plans must be taken from each individual account, however.

How do taxes work with RMDs?

In general you will pay taxes at your income tax rate on the amount of the distributions. However, certain exceptions apply.

What happens if you don’t take your required minimum distributions?

The penalties for not taking your required minimum distributions are stiff, to say the least. According to the IRS:

“If an account owner fails to withdraw a RMD, fails to withdraw the full amount of the RMD, or fails to withdraw the RMD by the applicable deadline, the amount not withdrawn is taxed at 50%.”

So, unless you want to lose half of the money that you were required to withdraw in a particular year, to need to stay on top of your RMDs and make sure to take them by the deadline.

Final thought

It may seem odd that the government forces you to withdraw some of your retirement savings each year, but the bottom line is that you worked hard for that money and were smart about saving it.

Instead of looking at it as a burden, think of it as a way to ensure you’re putting that money to good use to enjoy healthy and happy retirement years for yourself and your family.

Advertisement

More stories you might enjoy from Clark.com:

Best online banks: Free checking and high-interest savings accounts

Several online banks including Ally Bank, CIT Bank and Marcus by Goldman Sachs have recently lowered the yield on their high-interest savings accounts. 

CIT Bank’s Savings Builder account dropped to 2.30% APY in late June 2019. Despite the change, its rate and other online-only banks pay more interest compared to traditional banks. 

The average rate on savings accounts nationwide is only 0.10%, according to the FDIC.

Some Clark.com readers tell us they’ve moved their savings to Wealthfront’s FDIC-insured cash account, which offered 2.57% APY as of July 2019. Wealthfront is a robo-advisor investment service.

If you want to earn more interest and grow your savings, now is a great time to switch from a traditional bank to an online bank.

Many online-only banks are growing in popularity because they have lower fees and higher interest rates compared to the big banks — and they’re still a safe place to keep your money.

Advertisement

Depositing a check is easy with your bank’s mobile app, but there’s no way to deposit cash with most online banks.

Best online banks: Team Clark’s picks 

If you’re someone who never needs to walk into a bank or credit union, you may be able to bank 100% online like Clark.com senior writer Michael Timmermann who has accounts with Discover Bank and CIT Bank.

Discover’s cash back checking account has 1% debit card rewards, while CIT Bank’s savings interest rate is now well above 2%.

Best online banks: Table of contents 

Not ready to leave your bank or credit union completely? You can keep your checking with them and open just an online savings account. After all, that’s where you’ll be earning the most interest anyway.

Advertisement

Look at it this way: Some online banks pay a full 2% APY (annual percentage yield) more than big banks.

Here’s the difference over five years if you open up a savings account at a traditional bank and deposit $5,000, then fund an online savings account with $5,000:

Savings rates comparison

Traditional bank: 0.01% APY

Online bank: 2.05% APY

Year Total Year Total 1 $5,000.50 1 $5,102.50 2 $5,001.00 2 $5,207.10 3 $5,001.50 3 $5,313.85 4 $5,002.00 4 $5,422.78 5 $5,002.50 5 $5,533.95

Team Clark has identified some of the best online banks. All of them are FDIC-insured, which means that your deposits (like checking and savings) are protected up to the FDIC insurance limit.

Each depositor is insured to at least $250,000 per insured bank. Read more at FDIC.gov.

The banks on our list don’t nickel and dime their customers. They offer free checking with perks, top rates for online savings accounts, mobile banking tools and great customer service.

Read on for Team Clark’s picks and let us know about your favorite online bank in the comments below…

Best online banks: Team Clark’s picks 

Ally Bank 

Ally Bank offers 2.10% APY on savings for all balance tiers, interest checking with no monthly fees and 24/7 customer service. 

Checking

  • 0.60% APY on balances $15,000 and more, 0.10% below that
  • No monthly maintenance fees
  • Use Allpoint ATMs for free, plus $10 reimbursement per statement cycle for other ATM fees
  • Free standard checks

Savings

  • Online Savings Account: 2.10% APY on all savings tiers
  • High Yield Certificate of Deposit (CD): 2.55% APY for 12 months, no minimum balance

Discover Bank 

You probably associate Discover with cash back credit cards, but it also has a checking account with cash back rewards for debit card purchases. 

Checking

  • Earn 1% cash back on up to $3,000 in debit card purchases each month
  • No monthly fees or monthly balance requirements
  • Access more than 60,000 surcharge-free ATMs (Allpoint or MoneyPass networks)
  • No fees for insufficient funds, excessive withdrawals, falling below minimum balances and stop-payment requests
  • Free checks upon request

Savings 

  • Online Savings Account: 2.05% APY, no minimum deposit or monthly fees
  • 12-month CD: 2.40% APY, $2,500 minimum initial deposit

Capital One 

Online banking customers can deposit cash at select Capital One-branded ATMs and Capital One Cafes. 

Checking 

  • Earn 0.20% APY on 360 Checking account balances under $50,000
  • $0 minimum deposit and no monthly fees
  • Access to 39,000 fee-free Capital One and Allpoint ATMs

Savings 

  • 360 Money Market: 2.00% APY for balances of $10,000 or more, 0.85% APY for balances below $10,000
  • 360 Savings: 1.00% APY for any savings balance

Simple 

Simple is fee-free banking! There are no minimum balance requirements, and no maintenance, overdraft or monthly fees.

Checking 

  • Built-in budgeting tool with the Simple app
  • Fee-free online checking account, including no overdraft fees
  • Free access to Allpoint ATMs
  • Protected Goal Accounts with a $2,000+ balance earn interest

CIT Bank 

CIT Bank offers some of the nation’s highest interest rates on its savings accounts, but you must keep a $25,000 balance or deposit $100 a month to earn the best rate. 

Savings

  • Savings Builder: 2.30% APY if you maintain a $25,000 balance or deposit $100 per month
  • Money Market: 1.85% APY, $100 minimum opening deposit
  • No-Penalty, 11-Month CD: 2.05% APY, $1,000 minimum opening deposit

Marcus by Goldman Sachs 

Marcus by Goldman Sachs has a competitive rate on its savings account and no monthly maintenance fees. 

Savings 

  • Online Savings Account: 2.15% APY, $1 minimum deposit to earn interest
  • No-Penalty, 13-Month CD: 2.35% APY, 

    $

    500 minimum deposit 

Charles Schwab Bank 

Schwab Bank checking and savings customers get unlimited fee rebates from any ATM worldwide, but the checking account must be linked to a Schwab One brokerage account.

Checking 

  • High Yield Investor Checking: 0.40% APY
  • Unlimited ATM rebates worldwide
  • No service fees or account minimums
  • Linked to a Schwab One brokerage account

Savings 

  • High Yield Investor Savings: 0.50% APY for all clients
  • Unlimited ATM rebates worldwide
  • No service fees or account minimums

Once you’ve identified an online bank that meets your needs, follow Team Clark’s step-by-step guide to help you make the transition process as easy as possible.

More Clark.com stories you may like: 

Mint.com review: 7 ways to get the most from the free budgeting tool

Mint.com is a free, ad-supported money management tool that’s helped millions of Americans stay on budget for more than a decade.

The personal finance app is owned by Intuit, the company behind TurboTax and QuickBooks, and stands out from competitors like YNAB (You Need a Budget) and Personal Capital for its easy-to-use budgeting and bill tracking features.

What’s so great about Mint is that it brings together all of your accounts in one place to give you a snapshot of your financial life.

If you’ve been following money expert Clark Howard for a while, maybe you’ve heard him talk about how Mint’s website and mobile app can help you create and stick to a budget.

In Clark’s opinion, Mint is the best of the budgeting apps:

“Mint has stood the test of time and will help you categorize your spending in so many different ways, and so much of it is done automatically to help you get control of what you’re up to.”

Mint budgeting sample page

I’ve personally been using Mint.com since the early days. When I was working to pay off my $86,000 mortgage in two years, I would sign in several times a week to track my earnings and spending.

Over the years, I’ve learned a few tips and tricks that may help you get the most from Mint.com. Read on for the details…

1. Link as many accounts as you can

For Mint to give you the most accurate picture of your finances, you need to link as many bank accounts as you can, which requires providing login usernames and passwords.

That way, Mint can download and categorize your transactions, such as your credit card purchases.

“Login user name and passwords are stored securely in a separate database using multi-layered hardware and software encryption,” Mint said on its security FAQ page.

Advertisement

Mint also uses multi-factor authentication to protect your account. I’ll have more on that later on.

If you link your bank accounts, credit cards, mortgage and other loans, Mint will automatically calculate your net worth (the sum of all your assets minus your liabilities). You can track that number from the “Accounts” section on the Overview page.

2. How to add a manual account 

Mint works with most financial institutions, but there are times when you can’t automatically link an account.

For example, I have some investments with Personal Capital — one of Mint’s competitors — and Mint told me there’s no way to link my account like I can with Vanguard and Fidelity.

The workaround is the “Other Property” feature. Here’s how to add a manual account from your computer:

  • Click the Settings tab in the top black menu bar
  • Click Property in the left sidebar
  • Click the + Add Property button
  • Select the type of property you’d like to add: “Real Estate, Vehicle, Cash or Debt, or Other” and click Next
  • Enter the requested fields then, click “Add it”

Important note: Since any of your accounts that are added manually won’t be updated automatically, you need to remember to update that information yourself when the balances change.

3. Fix transactions that are categorized incorrectly

One of the best things about Mint.com is how it pulls your spending data and categorizes your transactions, which can help you see if you’re overspending in one particular area — like groceries, home improvement or entertainment.

I cut my food spending by $1,200 last year, thanks to my budgeting tools, after noticing that I was spending too much on groceries and dining out.

Mint has hundreds of default categories, but sometimes your transactions may be categorized incorrectly. Fortunately, you can edit them in just a matter of seconds:

  1. Click the Transactions tab
  2. Click the transaction you’d like to edit
  3. Click on “Edit Details” and then you can edit the description and/or category
  4. Click I’m Done

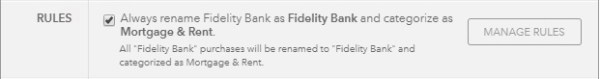
Those steps are for one-time transactions, but what if it’s a recurring transaction? You need the Renaming Rules feature. I had to figure this one out when Mint categorized my mortgage payment incorrectly.

Advertisement

To fix it: Click on your transaction, select “Edit Details” and change the category, then put a check mark next to “Always rename.”

Mint's Renaming Rules feature

4. You can track cash spending from the app 

If you put most of your expenses on a credit card and pay it off every month, staying on top of your budget with Mint is easy. All of those transactions are pulled in and categorized for you!

But what happens if you like to budget with cash? There’s a relatively new way to easily track those purchases with Mint.

Let’s say you go out to your favorite restaurant with co-workers and your bill is $20. You decide to pay cash instead of fooling with a credit card. When you leave the restaurant, open the Mint app or log in at home and select “Add a transaction.”

From there, just enter the details about the cash expense so that it’s reflected in the proper budget category.

How to track cash spending with Mint

5. Control alerts and notifications

When you sign up for Mint, you can expect to receive emails with bill reminders, credit score updates and general spending alerts.

These emails can be super helpful, especially if you have a history of forgetting to pay your bills, but I’ve found that the emails can be a little annoying at times. Do I really need an email every time I go $1 over my budget?

Luckily, there’s a way to control the alerts and notifications that you receive. Here’s how to do it…

From the Settings tab, click on Notifications. Make sure to click on “Change” next to “Send spending alerts” for a long list of alerts (unusual spending, over budget, bank fees, etc.) that you can adjust to your preferences.

Click on the Settings tab to adjust your notifications

6. Customize your Overview page to your preferences 

In recent years, I’ve really started to use Mint’s mobile app just as much as the website. It’s a great way to quickly check in on my budget while I’m on the go.

Advertisement

Mint’s Overview page lists your cash flow, transactions, accounts, bills, budgets, trends and even your credit score.

If you like to use Mint to monitor when your bills are due, you may want to see that information front and center. That’s why Mint makes it possible to customize your Overview page.

From the app, simply go to Settings and then Overview Settings to change the display order:

Change Overview page settings from the Mint app

7. Use your fingerprint as your password 

I mentioned that Mint uses multi-factor authentication a little bit earlier. The service says you may need to provide more than just your username and password when you sign in to your account.

“Rather than just a login and password, we also notify you of account changes with data from a second source or with information only you will have, like special security questions or a code from a text message or email.”

For app users, you can either use a passcode or your fingerprint to sign in. I recently switched to the fingerprint method and it works flawlessly.

RELATED: Ask Clark: How safe is Mint.com?

Final thought 

Budgeting is essential if you’re serious about reaching your financial goals. Mint provides everything you need to pay your bills on time, create a budget, check your credit score, set money goals and track your net worth.

The best part is that Mint is 100% free — all you have to do is put up with a few credit card advertisements.

If you have trouble knowing where your money goes, and more important, how to get your spending under control, add Mint to your smartphone and take back control of your wallet,” Clark says.

Do you use Mint or another personal finance tool to stay on budget? Tell us about it in the comments below! 

Advertisement

More Clark.com stories you may like: