Showing posts with label mint. Show all posts

Friday, August 2, 2019

Mint Mobile review: T-Mobile’s network for only $15/month

UPDATE: For a limited time, Mint Mobile is offering six months of service for the price of three. That’s only $60 total! Get unlimited talk, text and 8GB of 4G LTE data per month with this deal.

Mint Mobile, formerly known as Mint SIM, is a cell phone carrier that offers plans starting at $15 a month!

The mobile virtual network operator (MVNO) relies on T-Mobile’s towers to provide customers with the same coverage at a cheaper price, but is it worth the savings?

Everything you need to know about Mint Mobile

I signed up for Mint Mobile to find out. For the past 30 days, I used a Moto G6 smartphone to test Mint’s service in Atlanta, Georgia. In this review, I’ll detail my experience with factors like call quality, text performance and data speeds.

For some context, this was the first time that I’ve ever had service on T-Mobile’s network. Read on for my full review…

Mint Mobile review: Table of contents 

Plans and pricing

While T-Mobile and the other major wireless providers are now focused on unlimited data plans, many prepaid carriers like Mint Mobile have other data plans — often for a lower price.

But Mint Mobile doesn’t have a monthly payment option. Its plans are either for three months, six months or 12 months.

The regular price for a 3-month introductory plan starts at $45, which works out to $15 a month. That will get you 3GB of 4G LTE data per month and then unlimited data at lower speeds.

If you like the service, you can lock in the introductory pricing by signing up for a 12-month plan.

Other data options do exist. The 3-month introductory plan for 8GB of 4G LTE data per month is $60 ($20/month) or you can get 12GB of 4G LTE data per month for $75 ($25/month).

Advertisement

I took advantage of a limited-time deal: $20 for three months of service. See the latest offers at MintMobile.com!

Activation process 

I signed up for Mint Mobile online and my activation kit arrived a few days later. It took about 15 minutes for me to get up and running. The kit includes user-friendly instructions.

Here are the basic steps that I followed:

  • Inserted Mint SIM card into compatible device
  • Went to MintMobile.com/activation from my computer
  • Entered activation number from the back of the SIM card holder
  • Chose whether to get a new phone number or keep the existing one
  • Entered billing information and created an account
  • Configured data settings from phone’s settings menu
  • Restarted phone before using with Mint Mobile’s service

Phone selection

For my test, I used an unlocked Moto G6 smartphone. Most unlocked GSM phones (not CDMA) will work on Mint Mobile. You can check compatibility on Mint Mobile’s website.

If you don’t want to bring your own phone, here are some of the devices available for purchase:

  • Apple iPhone XS
  • Samsung Galaxy Note 9
  • Google Pixel 3 XL
  • Samsung Galaxy S9+
  • Motorola Z3 Play
  • LG V30 Plus
  • Motorola G6

We didn’t see any great phone deals when we checked Mint Mobile’s phone store. If you need a new phone, you may be better off buying a compatible device elsewhere and bringing it to Mint.

Call and text performance 

If T-Mobile has good coverage in your area, you shouldn’t have trouble with Mint Mobile because it uses the same towers.

As I mentioned at the top of my review, I never had T-Mobile or a T-Mobile MVNO before I signed up for Mint. I didn’t know what to expect, but I was pleasantly surprised.

I had only one dropped call and zero missing text messages throughout the 30-day testing period.

Advertisement

Whenever I test cell phone services, I ask my family and friends to rate the call quality. There were no complaints with Mint Mobile. Everyone could hear me loud and clear.

To see if Mint Mobile works in your area, follow this link to its coverage checker.

Note: Mint Mobile supports Wi-Fi Calling on select devices. If you’re in an area with unreliable coverage, you can connect to Wi-Fi and use your phone to call or text over that connection.

Mint Mobile coverage map

Mobile hotspot 

Mobile hotspot is a feature that isn’t offered by all prepaid carriers, but Mint Mobile is an exception. Tethering is allowed.

I tested out the mobile hotspot function with Mint and had no issues. I was able to watch a YouTube video without buffering or pausing after using mobile hotspot with my laptop.

Keep in mind that any high-speed data that you use when mobile hotspot is turned on will count toward your monthly limit.

Data speeds

Mint Mobile’s data speeds weren’t the fastest I’ve tested, but they were fast enough. I was able to watch videos, stream music, use maps for navigation and load websites without disruptions.

I used the Speedtest by Ookla app to find out the download and upload speeds. Here are the results:

We also used the Speedtest app to see if there was a major difference between Mint Mobile and T-Mobile’s data speeds. Although we had separate test devices, the download speeds were nearly the same.

Advertisement

From my experience, a download speed of 5-10 Mbps is perfectly fine for streaming video. Most of the download speed tests that I conducted with Mint Mobile were in the 20-25 Mbps range.

Upload speeds were less consistent with Mint, but that only matters if you regularly use your phone’s data to share files.

Customer service

My 30-day trial of Mint Mobile was problem-free, so I never had to call customer service. However, you can reach a customer service representative by dialing 213-372-7777.

If you don’t want to pick up the phone, there’s also chat and email support. The address is [email protected]

Although I found it easy to get started with this provider, you need to consider that there are no Mint Mobile stores. You can’t walk in anywhere and get customer service.

If that’s a priority for you, take a look at T-Mobile’s Metro brand for cheap wireless plans.

Pros and cons 

Pros and cons of Mint Mobile cell phone service

Pros Cons  Inexpensive data plans on T-Mobile’s network No unlimited high-speed data plan Mobile hotspot is allowed Some phones sold through Mint are overpriced Phone and email customer support No monthly payment option

Final thought

Over the past six months, I’ve tested Total Wireless, Unreal Mobile, Red Pocket Mobile and now Mint Mobile. I would probably rank Mint as my second favorite, behind Verizon MVNO Total Wireless.

Mint Mobile may be worth switching to if this sounds like you:

  • You know that T-Mobile’s coverage is good in your area
  • You don’t mind keeping track of your high-speed data (no unlimited plan)
  • You have a GSM device or are willing to buy a new one
  • You are willing to prepay for three, six or 12 months in advance

The price is right for Mint Mobile, but it’s not the only low-cost cell phone provider around. Learn about more of your options in Clark’s guide to the best cell phone plans and deals!

Advertisement

YNAB review: Is this budgeting app better than Mint?

SUCCESS STORY: After six months of using YNAB, a Clark.com reader wrote in to tell us that she is “no longer stressing over how to make it through the month.” She has an emergency savings for the first time and is working to get out of debt. The reader says she has used Mint and another program without success, but “neither program worked like YNAB.” Congrats and keep up the great work!

You Need a Budget, also known as YNAB, is a popular budgeting program that brings the envelope method into the digital age.

YNAB is based on four rules that have helped many subscribers stop living paycheck to paycheck and spend less money than they earn every single month.

In fact, YNAB claims that new budgeters save an average of more than $6,000 in their first year with the program.

YNAB review: Everything you need to know about the budgeting app 

I’ve been using free budgeting tools from Mint and Personal Capital for years, but I was reluctant to test YNAB because it costs $83.99 a year ($6.99 a month) after a 34-day free trial. There’s also an $11.99 monthly option.

I finally decided to try it out after this type of feedback from members of Clark’s Ditch Your Debt group on Facebook:

Tiffanie: We’ve used it for over 2 years, and LOVE it! Easy to enter transactions (especially on the fly); easy to import and approve transactions; always handy on my phone, which means I check it and update it frequently (important part of budgeting!); self-updates with great features; accessible on phone and online (work, home, etc); great tools to help you set & reach goals. Completely worth the monthly fee!! By using this, we save WAY more than the fee.

Don’t think you would ever pay for YNAB? I felt the same way, but stick with me. Even if you don’t plan to continue as a paying member, I believe the free trial may be worth your time.

If I had to choose just one word to describe my last month of budgeting with YNAB, “eye-opening” would be it.

This article details my personal experience with YNAB and how it compares to Mint, but I want to get started with a brief explanation of why this budgeting app isn’t like the others…

The 4 rules of YNAB

YNAB says it will help you budget like you’ve never done before, and that was true for me. YNAB’s method is based on four rules that can help you set up a budget, take control of your money and reach your financial goals.

Advertisement

  1. Give every dollar a job: When you receive a paycheck, assign it to your expense categories before you spend it.
  2. Embrace your true expenses: Set money aside every month for non-monthly expenses (property taxes, insurance premiums, holiday gifts, etc.) so that you’re ready when the bills come in.
  3. Roll with the punches: Things can and will go wrong! Move money around to cover categories where you overspend.
  4. Age your money: Stuck living paycheck to paycheck? By consistently spending less than you earn, you’ll work toward using last month’s pay on this month’s expenses.

Budgeting with YNAB for 30 days

YNAB’s rules were a little confusing to me at first, but it all started to make sense once I started my free trial.

Before I share more about my 30 days of budgeting with YNAB, I want to point out that the trial doesn’t require you to enter a credit card and there’s a 100% money-back guarantee for paid customers.

Problem syncing accounts 

Once I signed up on YNAB’s website, I immediately started following the prompts to connect my bank accounts to YNAB.

Like Mint and Personal Capital, YNAB links to your accounts to automatically import transactions. The service also has the option of adding unlinked accounts by starting with your current balance and manually entering transactions.

I ended up doing it the manual way because YNAB had trouble establishing an initial connection with several of my accounts.

People who are sensitive about sharing bank usernames and passwords may actually prefer the unlinked option. YNAB has a section of its website where you can read more about its security features.

Setting up my budget 

Moving on, I determined the amount of money to be budgeted for the month and started to give every dollar a job.

Here’s an example: If you have $2,000 to be budgeted, you have to assign all 2,000 of those dollars to your customizable categories, which are broken up into the following groups by default:

  • Immediate obligations
  • True expenses
  • Debt payments
  • Quality of life goals
  • Just for fun

This is a useful exercise because it requires you to prioritize your spending. If you have $2,000 to be budgeted and a $1,000 rent payment due in a few days, that leaves $1,000 to get you by until your next paycheck.

As you assign money to those categories, YNAB will encourage you to create short-term and long-term goals.

Advertisement

The simple color-coding with YNAB can also keep you on track. Green means you have dollars available, orange indicates that a category is underfunded and red is a sign that you’ve overspent.

YNAB sample budget on a desktop computer

Sticking to the plan 

The real fun began when I started spending money! Like I said, I had to manually enter transactions because of the synchronization issue, but it ended up being a lot less tedious than I expected.

I got into the habit of checking my category balance before buying anything and recording the transaction immediately after.

Use the YNAB app to add and categorize transactions

YNAB’s mobile app for Apple and Android devices is easier for me to navigate than the desktop version. In addition to categorizing new transactions in about five seconds, you can move money around as your priorities shift.

Here’s an example: During my free trial month, I got a surprise $700 home repair bill. That wasn’t in my home maintenance budget. As a result, I had to move money from several other categories to fund it — the third rule of YNAB.

The method empowered me to prioritize the repair over things like eating out, clothing, gifts and my vacation fund.

How much I saved 

I’m an analytical person to begin with, but checking with my budget and the dollar amount left in a particular category before making a purchase really helped me spend less over the last month.

Even with that $700 home repair bill, I was able to set aside money for my true expenses (non-monthly bills) and had $200 left.

Warning: There’s a learning curve!

If you’ve been budgeting with Mint or another tool, YNAB is going to require some effort to master — but it’s worth it!

Shortly after I signed up, YNAB sent me an email with an invitation to talk one-on-one with a coach for 15 minutes to answer some of my questions. That was a huge help!

Advertisement

In fact, that coach was even able to get someone to troubleshoot the account synchronization issues I had.

There are also 20-minute workshops every day where coaches answer your questions. I’ve shared a recorded workshop below because I think it’s one of the better ones:

There are other resources to help you budget successfully. YNAB has additional instructional videos, podcasts, forums, chat and help documents on its website. I’ve also seen YNAB respond to questions via Facebook and Twitter.

Even without phone support, I felt like I had all of the tools I needed to get the most out of the free trial.

YNAB: Summary of the pros and cons

Pros Cons  Customer service and tools Learning curve Easy-to-use mobile app Syncing accounts No advertising Price: $83.99 billed annually


YNAB vs. Mint: Which budgeting app is best? 

Money expert Clark Howard is a fan of Mint.com and says it’s great for automatically tracking your expenses. I’ve used Mint since 2010 and like how it has evolved to include bill reminders, credit score updates and net worth tracking.

However, I would have to say that YNAB does a better job with the budgeting component — that’s really all it does!

The more I used YNAB, the more I realized how it truly helps me manage my finances and proactively make smart decisions about what I spend money on and what I choose not to.

Mint, on the other hand, now seems like more of a report card after the money has already been spent.

The big advantage of Mint is that the service is free, but you do have to put up with credit card ads. There’s none of that with YNAB. You avoid the ads because it’s a paid service.

Advertisement

Is YNAB worth $83.99 a year? If it helps you get out of credit card debt or reach other financial goals, the answer is probably “yes.”

Here’s my suggestion: Take YNAB up on its 34-day free trial and spend some time to learn the method. Even if you don’t become a paying member, you may be able to apply the four rules on your own using a free budgeting tool.

Has YNAB helped you save more and spend less? Leave your review in the comments below!

More Clark.com stories you may like: 

10 things you need to know before you fly JetBlue Airways

During the summer and winter months, cheap flights from the Northeast to Florida can usually be found on JetBlue Airways. Although it is a low-cost carrier, the airline has made a name for itself for the amenities it offers travelers who appreciate the below-average airfares.

With its main base out of John F. Kennedy International Airport in New York, JetBlue controls much of the low-cost airfare market by giving snowbirds easy access to warmer climes.

JetBlue Airways: What to know before booking a flight

The New York City-based airline was incorporated in 1998 as NewAir, but changed its name to JetBlue shortly after. The sixth-largest airline in the nation, JetBlue boasted revenues of more than $7 billion in 2017, giving it one of the strongest balance sheets in the aviation industry.

Whether you’re thinking about booking a flight for the first time or contemplating whether to buy another ticket, here are some things to know about JetBlue.

1. Where does JetBlue fly?

JetBlue flies to 102 cities, including the Caribbean and Latin America. But the airline’s main concentration is on operations from six “focus” cities — Boston, Fort Lauderdale, Los Angeles, Orlando, New York and San Juan. See JetBlue’s route map here.

Several new international routes are being added in late 2018, including JFK to Mexico City (October) and expanded routes to Havana (November).

2. How are JetBlue’s fares structured?

JetBlue has three branded fares: Blue, Blue Plus and Blue Flex. Each of them include different options such as free checked bags, reduced change fees and TrueBlue point eligibility. All fares come with in-flight entertainment, snacks and non-alcoholic beverages — all free of charge.

3. What is JetBlue Mint?

JetBlue also offers a premium product called Mint. With Mint, you get “lie-flat” seats that allow you to get some serious shuteye on long flights as well as “artisanal” dining options like locally curated ice creams and exclusive chocolate bars from Raaka.

On most jets, JetBlue has 16 fully lie-flat seats, four of which are located in suites with a privacy door. The airline markets Mint to transcontinental business travelers, and no wonder: Mint launched in 2013 with one-way seats starting at $599.

For more about JetBlue’s fare structure, see the chart below.

Advertisement

4. JetBlue is the only major airline with a Customer Bill of Rights

 If anything ever goes haywire for you on a JetBlue flight, passengers have a written recourse that they can use to get monetary compensation. That’s what makes JetBlue’s Customer Bill of Rights so useful.

The Bill of Rights explicitly outlines how much money fliers get in the case of a ground delay or overbooking. This handy document will help to cut down on confusion and compensation expectations.

5. JetBlue offers free Wi-Fi

The airline offers free Wi-Fi on all domestic flights. The airline has branded the service “Fly-Fi” and bills it as gate-to-gate mobile and internet service for passengers.

Free Wi-Fi is available on all of JetBlue’s 227 Airbus A320s, A321s and Embraer 190s, according to the airline.

6. JetBlue has a Best Fare Guarantee

The carrier promises that it will always display its cheapest fares on its own site. “[If] by any chance you find a lower JetBlue fare elsewhere on the same day of purchase, we’ll give you a $100 credit good for travel on JetBlue,” the airline says on its website.

This is important because some major airlines hide their cheapest fares on their own website but allow them to be searchable on some of the other travel sites like Kayak, Expedia and Priceline.com to compete with low-cost carriers.

RELATED: Delta Air Lines also has a Best Fare Guarantee

7.

How much legroom do JetBlue’s seats offer?

JetBlue is fond of saying that its jets offer “the most legroom in the main cabin of all U.S. airlines, based on average fleet-wide seat pitch.” That’s because JetBlue’s fleet includes the Brazilian-built Embraer 190 (E190), which offers customers the roomiest interior of any narrow-body aircraft.

For a fee, JetBlue also offers Even More Space seats, which give travelers additional legroom.

RELATED: How much legroom does your favorite airline have?

Advertisement

8. What is JetBlue’s baggage policy?

JetBlue has gone up on its baggage prices, effective Monday, August 27 2018: For Blue fares, your first checked bag will cost you $30 (it was $25) if you booked after that date. The change also means your second bag will be $40. For Blue Plus, your first checked bag is included and the second bag is $40. For Blue Flex fares, two checked bags are included.

For Mint fares, two checked bags up to 70 pounds each are included. For all fares, any additional bag will cost $150 (a $50 increase).

As for size, bags that exceed 62 inches overall (length + width + height) or weigh more than 50 pounds will be assessed a fee.

For carry-on bags, each passenger is allowed one bag and one personal item (purse, briefcase, laptop, etc.). Personal items can’t be larger than 17 inches long, 13 inches wide and 8 inches high and must be able to fit under your seat. 

9. How do customers view JetBlue’s service?

When it comes to customer satisfaction, JetBlue came in tied for second place among major U.S. carriers in the American Customer Satisfaction Index report that was released in April 2018. Last year it was #1.

Company 2017 2018 Change Southwest 80 80 0% Alaska 78 79 1% JetBlue 82 79 -4% Allegiant 71 74 4% American 76 74 -3% Delta 76 74 -3% All others 74 73 -1% United 70 67 -4% Frontier 63 62 -2% Spirit 61 62 2%

10. How to save money on JetBlue flights

  • If you can, book online: JetBlue adds $25 per person to fares purchased by phone.
  • Check their deals page: Use JetBlue’s Deals page, its Best Fare Finder and the JetBlueCheeps account to save.
  • Become a TrueBlue member: JetBlue’s frequent flyer program, TrueBlue, offers numerous perks for members, including exclusive fares and upgrades.

Have you flown JetBlue? Tell Team Clark about your flying experience on Facebook, Twitter or below in the comments section!

Here are some more travel-related articles you might enjoy from Clark.com:

Mint.com review: 7 ways to get the most from the free budgeting tool

Mint.com is a free, ad-supported money management tool that’s helped millions of Americans stay on budget for more than a decade.

The personal finance app is owned by Intuit, the company behind TurboTax and QuickBooks, and stands out from competitors like YNAB (You Need a Budget) and Personal Capital for its easy-to-use budgeting and bill tracking features.

What’s so great about Mint is that it brings together all of your accounts in one place to give you a snapshot of your financial life.

If you’ve been following money expert Clark Howard for a while, maybe you’ve heard him talk about how Mint’s website and mobile app can help you create and stick to a budget.

In Clark’s opinion, Mint is the best of the budgeting apps:

“Mint has stood the test of time and will help you categorize your spending in so many different ways, and so much of it is done automatically to help you get control of what you’re up to.”

Mint budgeting sample page

I’ve personally been using Mint.com since the early days. When I was working to pay off my $86,000 mortgage in two years, I would sign in several times a week to track my earnings and spending.

Over the years, I’ve learned a few tips and tricks that may help you get the most from Mint.com. Read on for the details…

1. Link as many accounts as you can

For Mint to give you the most accurate picture of your finances, you need to link as many bank accounts as you can, which requires providing login usernames and passwords.

That way, Mint can download and categorize your transactions, such as your credit card purchases.

“Login user name and passwords are stored securely in a separate database using multi-layered hardware and software encryption,” Mint said on its security FAQ page.

Advertisement

Mint also uses multi-factor authentication to protect your account. I’ll have more on that later on.

If you link your bank accounts, credit cards, mortgage and other loans, Mint will automatically calculate your net worth (the sum of all your assets minus your liabilities). You can track that number from the “Accounts” section on the Overview page.

2. How to add a manual account 

Mint works with most financial institutions, but there are times when you can’t automatically link an account.

For example, I have some investments with Personal Capital — one of Mint’s competitors — and Mint told me there’s no way to link my account like I can with Vanguard and Fidelity.

The workaround is the “Other Property” feature. Here’s how to add a manual account from your computer:

  • Click the Settings tab in the top black menu bar
  • Click Property in the left sidebar
  • Click the + Add Property button
  • Select the type of property you’d like to add: “Real Estate, Vehicle, Cash or Debt, or Other” and click Next
  • Enter the requested fields then, click “Add it”

Important note: Since any of your accounts that are added manually won’t be updated automatically, you need to remember to update that information yourself when the balances change.

3. Fix transactions that are categorized incorrectly

One of the best things about Mint.com is how it pulls your spending data and categorizes your transactions, which can help you see if you’re overspending in one particular area — like groceries, home improvement or entertainment.

I cut my food spending by $1,200 last year, thanks to my budgeting tools, after noticing that I was spending too much on groceries and dining out.

Mint has hundreds of default categories, but sometimes your transactions may be categorized incorrectly. Fortunately, you can edit them in just a matter of seconds:

  1. Click the Transactions tab
  2. Click the transaction you’d like to edit
  3. Click on “Edit Details” and then you can edit the description and/or category
  4. Click I’m Done

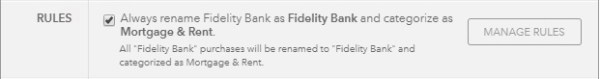
Those steps are for one-time transactions, but what if it’s a recurring transaction? You need the Renaming Rules feature. I had to figure this one out when Mint categorized my mortgage payment incorrectly.

Advertisement

To fix it: Click on your transaction, select “Edit Details” and change the category, then put a check mark next to “Always rename.”

Mint's Renaming Rules feature

4. You can track cash spending from the app 

If you put most of your expenses on a credit card and pay it off every month, staying on top of your budget with Mint is easy. All of those transactions are pulled in and categorized for you!

But what happens if you like to budget with cash? There’s a relatively new way to easily track those purchases with Mint.

Let’s say you go out to your favorite restaurant with co-workers and your bill is $20. You decide to pay cash instead of fooling with a credit card. When you leave the restaurant, open the Mint app or log in at home and select “Add a transaction.”

From there, just enter the details about the cash expense so that it’s reflected in the proper budget category.

How to track cash spending with Mint

5. Control alerts and notifications

When you sign up for Mint, you can expect to receive emails with bill reminders, credit score updates and general spending alerts.

These emails can be super helpful, especially if you have a history of forgetting to pay your bills, but I’ve found that the emails can be a little annoying at times. Do I really need an email every time I go $1 over my budget?

Luckily, there’s a way to control the alerts and notifications that you receive. Here’s how to do it…

From the Settings tab, click on Notifications. Make sure to click on “Change” next to “Send spending alerts” for a long list of alerts (unusual spending, over budget, bank fees, etc.) that you can adjust to your preferences.

Click on the Settings tab to adjust your notifications

6. Customize your Overview page to your preferences 

In recent years, I’ve really started to use Mint’s mobile app just as much as the website. It’s a great way to quickly check in on my budget while I’m on the go.

Advertisement

Mint’s Overview page lists your cash flow, transactions, accounts, bills, budgets, trends and even your credit score.

If you like to use Mint to monitor when your bills are due, you may want to see that information front and center. That’s why Mint makes it possible to customize your Overview page.

From the app, simply go to Settings and then Overview Settings to change the display order:

Change Overview page settings from the Mint app

7. Use your fingerprint as your password 

I mentioned that Mint uses multi-factor authentication a little bit earlier. The service says you may need to provide more than just your username and password when you sign in to your account.

“Rather than just a login and password, we also notify you of account changes with data from a second source or with information only you will have, like special security questions or a code from a text message or email.”

For app users, you can either use a passcode or your fingerprint to sign in. I recently switched to the fingerprint method and it works flawlessly.

RELATED: Ask Clark: How safe is Mint.com?

Final thought 

Budgeting is essential if you’re serious about reaching your financial goals. Mint provides everything you need to pay your bills on time, create a budget, check your credit score, set money goals and track your net worth.

The best part is that Mint is 100% free — all you have to do is put up with a few credit card advertisements.

If you have trouble knowing where your money goes, and more important, how to get your spending under control, add Mint to your smartphone and take back control of your wallet,” Clark says.

Do you use Mint or another personal finance tool to stay on budget? Tell us about it in the comments below! 

Advertisement

More Clark.com stories you may like: