Showing posts with label need. Show all posts

Friday, August 2, 2019

8.1.19 How to buy a home; Do you need cell phone insurance?; Working while in college

8.1.19 How to buy a home; Do you need cell phone insurance?; Working while in college


Clark's 13-year-old son was all over getting a cell phone protection plan. We're so connected to our devices that when in a cell phone store, we're susceptible to the pitch to buy their junk insurance product. Don't do it. Cell phone insurance is horrible, trashy junk. Don't do it. It's overpriced, and you have a big deductible for what's usually a refurbished replacement phone. Have wide insurance in your life disability. Use a credit card hat provides free cell phone insurance when you use it to pay your monthly cell bill. 

There's one thing higher and trade education students can do to boost their chances of good-paying jobs after school - work while in school. ?Working in college makes for higher paid grads. Northeastern University grads tend to easily get good jobs after school because working is built into the curriculum. Students alternate semesters with working full-time. The degree takes an extra year, going year-round. New grads have years of experience in their field of study. Having work experience provides maturity so valuable to employers. Clark was a full-time working night student in college and grad school. That work experience served him well, allowing him to retire (the 1st time) at age 31.

Learn more about your ad choices. Visit

People have issues with financing, builders, selling, and buying used homes. There are many confusing moving parts. Clark discusses 9 steps to buying a home involving credit, qualifying and shopping for loans, shopping homes, negotiating etc. Local communities have design rules that have crushed affordability for first time home buyers. In dense urban areas, the value of land drives the cost of homes. So out-of-date rules on land use create many inefficiencies, including affordability. The next wave of urban planning should take into account creating efficiencies that will allow more affordable, smaller single-family housing in metro corridors.Clark's 13-year-old son was all over getting a cell phone protection plan. We're so connected to our devices that when in a cell phone store, we're susceptible to the pitch to buy their junk insurance product. Don't do it. Cell phone insurance is horrible, trashy junk. Don't do it. It's overpriced, and you have a big deductible for what's usually a refurbished replacement phone. Have wide insurance in your life disability. Use a credit card hat provides free cell phone insurance when you use it to pay your monthly cell bill.There's one thing higher and trade education students can do to boost their chances of good-paying jobs after school - work while in school. ?Working in college makes for higher paid grads. Northeastern University grads tend to easily get good jobs after school because working is built into the curriculum. Students alternate semesters with working full-time. The degree takes an extra year, going year-round. New grads have years of experience in their field of study. Having work experience provides maturity so valuable to employers. Clark was a full-time working night student in college and grad school. That work experience served him well, allowing him to retire (the 1st time) at age 31.Learn more about your ad choices. Visit megaphone.fm/adchoices Read more

6 things to know about Haven Life

Haven Life is one of a new breed of life insurance players removing the friction from the life insurance shopping process. With Haven, you do everything online — from getting a quote to e-signing your documents.

Here’s what you need to know about Haven Life

Buying life insurance is something so many of us know we need to do, but we just don’t get around to it. That’s partly because the traditional life insurance thing is cumbersome.

You used to have to sit down with an agent — either in your home or on the phone — and answer questions about your general health. Then you had to agree to submit to a medical exam.

Once the exam was scheduled, you had to get ready to be poked and prodded by needles. Then, you had to wait for weeks for the lab results to come back and the policy to be written.

But Haven Life has re-imagined the whole idea of buying life insurance. Here’s what you need to know before you get a quote:

Table of contents

  1. Getting a quote online
  2. Coverage limits
  3. Term life calculator
  4. No medical exam policies
  5. A.M. Best rating
  6. Haven Life Plus

1. You can get a quote online and don’t ever have to talk to an agent

Haven Life has completely automated the process for buying life insurance. There’s no old-school agent you have to deal with at any step of the process. From getting a quote to finalizing your coverage, it’s all done online from any smartphone or computer.

Here are a few more ways Haven has simplified the shopping process and made it more customer-friendly:

  • Paperless processing
  • All policies sold commission-free
  • Only sells term life insurance — no whole life
  • Level premiums mean you pay the same amount each month and it never goes up

If you have any questions during the application process, you can stop at any time and get help in several ways: via chat, phone (1-855-744-2836) or email ([email protected]).

2. You can get up to $3 million in coverage

If you’re a U.S. citizen under age 60, you can get up to $3,000,000 in term life insurance coverage.

However, if you’re either over 60 but younger than 64 or an eligible non-U.S. citizen, you can qualify for up to $1,000,000. Similar coverage restrictions apply if you get a no medical exam term policy — but more details on that in a moment.

Advertisement

3. Haven Life’s term life calculator helps determine coverage needs

Haven Life term life insurance needs calculator

Figuring out how much life insurance you need to purchase is something that stumps a lot of people shopping for a policy.

As a general rule of thumb, money expert Clark Howard recommends buying an amount equal to 10 times your salary, before taxes.

But for an answer to the question of how much to buy that’s tailored specifically to your situation, Haven offers a term life insurance needs calculator.

When you use the calculator, you’ll be asked to input the following info:

  • Gender
  • Date of birth
  • State of residence
  • Nicotine use
  • Health condition
  • Annual income
  • Family size
  • Total amount of debt

The calculator will then kick back a recommended coverage amount for a certain term of years, along with an estimated monthly premium rate.

4. Haven Life offers no medical exam term policies

A big part of the appeal of Haven is that you don’t have to undergo a medical exam to get a term life policy.

Select qualified applicants up to age 59 can finalize coverage online without the need to have a physical exam or a blood test like you would with other insurers.

Certain candidates, however, may still need to pass medical underwriting, depending on a variety of factors.

While you can purchase up to $3 million in coverage if you medically underwrite, Haven caps its no medical exam term life policies at $1 million of coverage.

5. Haven Life is underwritten by MassMutual, an A++ rated company

When it comes to selecting a life insurance company, strength and financial stability are very important. You want to be sure the company you’re buying a policy from will be around for a long time to come.

Advertisement

That’s because if you die while the policy is in force, you have to know that the insurance company will be financially solvent and around to pay on your claim.

Of course, nobody can see the future — but we have the next best thing in A.M. Best, a credit rating company that focuses on the insurance industry. Using a proprietary system, A.M. Best grades insurance companies on a scale from A++ to F.

Haven Life policies are underwritten by Massachusetts Mutual Life Insurance Company (MassMutual), a company that’s been around for 160 years and gets an A++ from A.M. Best. With that kind of history and financial strength, you can rest assured that Haven Life and MassMutual will be around to pay on claims should you die prematurely.

Remember, getting a grade of A++ is as much assurance that a company will stand the test of time as you can possibly get.

6. Haven Life Plus offers free add-on services on your policy

When you get a term life policy from Haven, you get so much more than just insurance to provide for your beneficiaries if you die. You also get a suite of free additional offerings called Haven Life Plus.

Haven Life Plus is an insurance rider that sits on top of your existing policy. It offers a broad range of freebie perks valued at more than $300. These perks touch on estate planning, on-demand health services and emergency planning, among other things:

  • Will creation from Trust & Will ($129 value)*
  • On-demand fitness app Aaptiv ($99 value)
  • Timeshifter app that helps fight jet lag ($24.99 value)
  • Free estate planning/secure online vault from LifeSite ($80 value)
  • 15% discount on any single CVS MinuteClinic service

* Offer void in North Carolina

The Haven Life Plus rider is not available in Florida, New York, North Dakota, South Dakota and Washington.

Final thought

Having a life insurance policy in place is important if you have a family or spouse that depends on your paycheck. If you die prematurely, they’ll face a tremendous struggle to replace your income. That’s why life insurance offers such great peace of mind.

But times are changing and the modern life insurance customer wants a simplified shopping process. Haven Life delivers that hands down. And, Haven bolsters its offerings with a nice suite of freebies and perks.

Advertisement

Still not sure you need a policy? Read our piece titled “What is term life insurance and should I buy it?” for the final word.

Then when you’re ready to get shopping, be sure to check out our guides on how to buy term life insurance and the best life insurance companies before you make up your mind.

More stories you might enjoy from Clark.com:

When do you need a travel agent?

It’s become second nature for many of us to book airline tickets, car rentals and hotel stays ourselves. But there are certain times when you really need to hire a travel agent.

Beyond the basics, planning other travel needs like ground transportation for groups, tours, theater visits, theme parks and concerts to coordinate with your itinerary can take up tons of time.

A retired travel agent explains when you need to hire one

I’m a retired travel agent. Recently, I spent countless (too many) hours planning hotel nights, rail travel and tours to see as much of Ireland as I could in one fell swoop over just over two weeks.

Even I’ll admit that the time spent was a bit excessive. Studies indicate that travelers spend 30 hours researching and preparing for a trip and visit up to 38 websites before actually making a reservation. I may have exceeded those averages.

It wasn’t that I tried to over-plan and fill each and every day — I just wanted to know that all of the experiences would appeal to my style of travel (no big bus tours, ample free time, no evenings planned).

If I had not been an agent myself, I probably would have hired one for my Ireland visit. Here’s when having someone working on your trip can be super helpful…

  • Travel agents can guide an inexperienced traveler through taking their first trip overseas, when traveling to a destination where tourism is less developed, or when the trip is to multiple cities.
  • An agent can help you out of jams should you miss a flight connection, face a canceled flight, or for assistance when natural disasters strike like major storms, earthquakes, or civil strife that have an effect on your plans.
  • A travel agent can often help find the best prices on tours and cruises with exclusive promotional offers and deals. Estimated savings can be anywhere from $500 to $1,000 on international airfare and tours.
  • An agent will inform you about any necessary documents you may need: visas, vaccinations, and restrictions if you’re traveling to a religious or conservative country.
  • A travel agent can offer travel insurance options to cover anything that could arise on your trip.
  • An agent is key when you want to embark on a trip of a lifetime, like the Tokyo Summer Olympic, the 2020 World Expo in Dubai, the inaugural sailing of spectacular ships, Disney vacations or The Passion Play at Oberammergau, to name a few.
  • When your trip involves coordinating with a group of friends or family members across the county, an agent can keep things organized.
  • Cruise experts can help maneuver through the many ship options based on your group or multi-generational needs. Some ships offer refundable vs. non-refundable rates and guaranteed cabins vs. cabins with free perks. Which option is best for your needs? That’s where an agent’s expertise is key.

How much does a travel agent cost?

Can a travel agent help save time with trip planning? Yes, most definitely!

Can a travel agent save you money? Probably, but there will usually be some expenses on the front end.

You should expect for an agent or agency to collect fees for certain services. Ask your agent for specifics. Here are some averages:

  • Airline tickets: $25-$50 domestic round-trips or multi-city; higher for an international ticket (per itinerary)
  • Cruises: $30-$50 per person
  • Tours: $100 per person up to 8 nights; $175 9-13 nights; $250 14 or more nights
  • Last-minute: $100 per person (for trip arrangements for travel within two weeks of departure)

Some travel agents don’t charge any fees. That’s because they earn commissions through partner vendors.

Advertisement

Certain agencies may accept a planning deposit for custom trips above and beyond one destination or ones that may require various modes of transport and coordination.

A portion of that deposit or the full deposit amount may be refunded after the trip has been completed. That deposit (which is around $100 in most cases) may be asked for as a means to prevent a customer from booking elsewhere after the agent has done all the research.

How to find a good travel agent

So, how do you find a good travel agent?

Ask family, friends and co-workers who love to travel for a recommendation. Chances are they use the services of an agent.

You can also look for an agent at TravelSense.org, operated by the International Air Transport Association. Seek out agents/agencies with the ASTA (American Society of Travel Agents) accreditation. There, you can filter agents by their specialty.

Each year, Travel + Leisure’s editors compile the A-List, a curated selection of the world’s best travel agents and destination specialists that are organized by worldwide regions as well as by specialty trips like fly-fishing, scuba diving, safaris and honeymoons.

Need help with cruise planning? Enter your zip code at Cruising.org to find a CLIA Certified Agent (Cruise Lines International Association) near you.

Final thought

Most trips probably don’t require the services of a travel agent, but if you’re planning something that involves any of the complications outlined above you might benefit from the help. These are people who do this for a living, so sometimes it’s best to leave the planning to a professional.

More stories you might enjoy from Clark.com:

How to make an extra $100 in a day

If you need a little more money in your pocket to see you through to the end of the month, there are a lot of ways you can make an extra $100 a day — and some of them you can do online from home.

Check out these ways to make $100 today!

Got a little bit of extra time on your hands? Just follow this advice to monetize those spare moments. Before you know it, you’ll be on your way to putting an extra Ben Franklin in your billfold.

As you read through this list, keep in mind that all of the figures about potential earnings are before taxes.

Table of contents

Pet sitting/walking: Rover and Wag

Rover homepage

  • Potential earnings: $16/hour
  • Work 6.25 hours in one day to earn $100

Are you an animal lover? Then you might be a good candidate to sell your on-demand services as a pet-sitter or a dog walker through a variety of apps including Rover and Wag.

To qualify for the job, you typically just have to demonstrate prior experience with animals, be competent at using collars and harnesses, and demonstrate that you can remain in control of unpredictable situations with dogs.

The average hourly salary for a dog walker with Rover is $16, according to Glassdoor. But the earnings could be higher if you manage to take more than one dog out for a walk at a time.

Nanny for hire: SitterCity

SitterCity homepage

  • Potential earnings: $17.50/hour
  • Work just under 6 hours in one day to earn $100

If you’re good with kids, you might consider being a babysitter or nanny for hire. SitterCity is one app that can connect you with families in need of child care. Just log on and complete a profile with your bio, preferences, availability and a photo. It’s free to register!

According to SitterCity, the average wage for a nanny in June 2019 was $17.50.

Advertisement

Similar services you may want to check out include Bambino, UrbanSitter, and SeekingSitters.

Take online surveys: MTurk 

Amazon M Turk screen

  • Potential earnings: $7.30/hour
  • Work 13 and a half hours in one day to earn $100

If you’re wondering how to make $100 a day online, don’t overlook using Amazon as part of your strategy. Amazon’s Mechanical Turk (MTurk) gives you the opportunity to take surveys and do other kinds of micro-gigs for a small cash reward.

One of our staff members did a deep dive on working MTurk gigs. He spent 30 minutes a day for a month and managed to earn $110! That works out to be about $7.30/hour. You can read all about his experience here.

However, we should make one final point: While it’s easy to complete MTurk tasks while sitting on the couch watching TV, the work can be repetitive and boring. You probably wouldn’t want to plan on doing this more than a few hours a day.

Deliver groceries: Shipt and Instacart

Shipt homepage

  • Potential earnings: $16 to $22 an hour
  • Work 4 and a half hours in one day to earn $100

Apps like Shipt and Instacart give you the opportunity to pick up grocery orders and deliver them to people’s homes. All you need to get started is to be 18+, have a smartphone, valid driver’s license, auto insurance and a reliable vehicle — plus be able to lift about 40 pounds.

Shipt says you can earn anywhere between $16 to $22 an hour. There’s the potential to earn even more when you factor in tips.

Do small tasks online: Fiverr

fiverr homepage

  • Potential earnings: $20/hour (assuming you can do four tasks in an hour)
  • Work 5 hours in one day to earn $100

No matter what kind of skill set you have, you can probably find a way to make $100 a day online with Fiverr!

Advertisement

Fiverr is a site where people post a variety of tasks they’ll do starting at $5 a pop. When we checked, we found the following services being offered:

  • Make an animated logo video intro
  • Give personalized dating advice
  • Perform property title searches
  • Scrape business data with emails from Google Maps
  • Proofread and edit any text up to 1,000 words

Some of these tasks might only take about 15 minutes or so. The key is to know which ones fit that criteria.

Once you cull the herd, you’d have to perform about 20 of them in a day. It sounds like a lot, but it is possible — particularly if you’re proficient in whatever it is you do. There’s a market for just about everything out there.

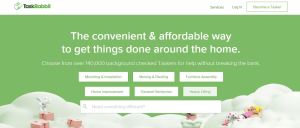
Pick up odd jobs: TaskRabbit

TaskRabbit homepage

  • Potential earnings: $25/hour
  • Work 4 hours in one day to earn $100

Are you good with furniture assembly, mounting and installation, moving and packing or general handyman jobs? TaskRabbit lets you pick up odd jobs in those and other categories.

The pay varies by job. Here are some sample rates advertised on the service’s homepage:

  • Assemble a table/desk – starting at $49
  • Mount a TV or mirror- starting at $56
  • Move boxes via truck – starting at $51
  • Clean bathroom/kitchen – starting at $54

You’re not paid by the hour, but by the task — no matter how long it takes to complete. So let’s say it takes you two hours to mount a flat-screen TV on a wall in somebody’s home. If you do that in two homes over the span of about four hours, you’ll have your $100.

Online tutoring/teaching: Chegg and Udemy

Chegg homepage

  • Potential earnings: $20/hour
  • Work 5 hours in one day to earn $100

If you’re looking to make $100 a day on the internet, either tutoring online or creating your own online classes could be a good ongoing source of income for you. Chegg is a leader in the former space, while Udemy dominates the latter.

Sites like these allow you to virtually connect with students in need of lessons and do the teaching right from your home computer. This is a particularly good job for teachers who may be off during the summer.

Advertisement

According to Chegg, pay rates start at $20+ an hour.

Ride-share driver: Uber and Lyft

Uber homepage

  • Potential earnings: $15 to $16 an hour
  • Work just over 6 hours in one day to earn $100

It’s entirely possible to make a living driving for ride-share services like Uber and Lyft — but you only need a handful of hours to make $100 fast!

You can expect to make estimated earnings of $15 to $16 an hour by being a ride-share driver, according to Glassdoor. Meanwhile, you can read about money expert Clark Howard’s experience of driving for both services here.

Final thought

It’s not that difficult to make $100 a day. The key is to know the opportunities that are out there and hone in on what makes sense for your life.

Maybe after reading this article, you’ll decide that you need to make a lot more than $100 in a day. In that case, you may want to see our piece that outlines 6 steps to make $1,000.

Meanwhile, if you specifically want to start earning money from home, check out our Work From Home Guide.

More Clark.com stories you may like: 

The IRS is rolling out a new W-4: What you need to know

The Internal Revenue Service has announced its intention to roll out a new W-4 form soon — and it might mean huge headaches for the millions of working Americans who use the form to determine how much of their pay should be withheld to pay their federal income taxes.

Pretty much whenever you start a new job, you’re required to fill out a Form W-4, officially the “Employee’s Withholding Allowance Certificate.”

Here’s what you need to know about the proposed new W-4…

Proposed new W-4 tax withholding form is a lot more complicated

Why do I have to fill out a W-4 form?

The W-4 lets your employer know how much of what you earn for your work they should withhold to pay the federal taxes on your wages.

If you fill out the form correctly, ideally you should neither owe too much nor get a huge refund when you file your taxes for the prior year.

The form has remained pretty much unchanged for quite some time, but the IRS now says it intends to have an updated, more complex form for the year 2020.

How will the new W-4 form differ from the current one?

Take a look at the current W-4 form (which will probably look familiar if you’ve had a job any time recently) and the proposed new form. Keep in mind that the proposed form below could change before it is officially released:

Current W-4 form Proposed new W-4 form

As you can see, the proposed form is quite a bit longer than the existing one and contains a lot more information, even though the IRS said in its release about the changes that “The primary goals of the new design are to provide simplicity, accuracy and privacy for employees while minimizing burden for employers and payroll processors.”

But the length of the form isn’t the biggest difference: Allowances are going away.

Currently, you are asked to fill out a worksheet which gives you a number of allowances to fill in. Allowances are exemptions that reduce the amount of tax your employer withholds. The more allowances you have, the more of your pay you actually take home.

Advertisement

On the proposed new form, you’ll be asked to fill in dollar amounts for:

  • Income from other jobs in the household
  • Expected income tax credits
  • Itemized and other deductions
  • Non-wage income like interest, dividends and retirement income

As USA Today puts it, “Filling out the new form will be a lot like doing your taxes again.”

How often do I have to fill the W-4 out?

While the new form will undoubtedly be more complicated, it should mean that that withholding amounts will be a lot more accurate. Money expert Clark Howard says that’s a good thing when mid-April rolls around:

“I’d prefer that you get no refund at all. If you are getting one, it means that you’ve made an interest-free loan to the government and your money has been working for them — not you — all year long.”

So, because of that improved accuracy it will likely be beneficial for you to fill out a new W-4 — as painful as it might be — every year or so since your financial situation is likely to change over time.

Final thought

With all of this said, it’s remotely possible that these proposed changes don’t see the light of day any time soon. The new form was slated to be rolled out this year, but the sample was met with concern from tax and payroll professionals.

The IRS announced that is was taking comments on the proposed design until July 1, so they’re likely processing all of that information now. Team Clark will keep you up to date on everything when and if it becomes official.

Listen to Clark talk about the upcoming changes to the W-4 form here.

More stories you might enjoy from Clark.com:

Want to work from home? Williams-Sonoma is hiring

Williams-Sonoma, the home furnishings and gourmet cookware specialty store, is hiring right now for customer service associates in several cities.

All of these are work-from-home jobs. The retailer is known to go on hiring sprees from time to time and Clark.com loves to spread the word about remote jobs.

Williams-Sonoma is hiring for work-from-home positions

The company is hiring “Customer Service Agents” who happen to live in the same states as one of their Customer Care Centers.

As a Customer Care Agent, you’ll take calls to assist people with placing orders, making returns, scheduling deliveries and more, according to the job description.

You can expect to communicate with customers via phone, email and live chat to help them with whatever they need. The job posting also says that you’ll get growth/promotional opportunities as well as a 40% discount on most merchandise.

Here are details about the pay and benefits for this position:

  • $12/hour
  • Paid training from home
  • Fun contests, rewards and recognition programs

You’ll need to have a computer/PC/Mac with compatible OS, a computer USB headset with microphone and a minimum internet upload speed of 6 Mbps and 10 Mbps of download speed before training.

Here are some available openings on Williams-Sonoma’s website:

If you need to work from home only during a certain time, Williams-Sonoma also has night shifts available on the customer service team. Learn more about this position and apply now on Williams-Sonoma’s website!

More Clark.com stories you may like: 

Can freezing your credit hurt your credit score?

Anyone who follows money expert Clark Howard knows that his number one suggestion for keeping your finances safe from criminals is to freeze your credit.

A credit freeze, which is also sometimes called a security freeze, is a way of locking down your credit reports, which makes it nearly impossible for criminals to open new accounts in your name. This is because most creditors need to look at those reports in order to make the decision whether to extend you credit or not.

We here at Team Clark know that thousands of you have already frozen your credit or are considering it, in part because of all of the questions we get from people related to credit freezes. Chief among those questions is: “Can freezing my credit hurt my credit score?”

Does freezing your credit hurt your credit score?

Freezing your credit has no direct impact on your credit score. It certainly will not lower it. Indirectly, freezing your credit can actually help improve your credit score (or at least keep it from dropping) because it prevents unwanted credit lines from being opened in your name.

A credit freeze also does not “freeze” your credit score where it is. It will continue to rise and fall depending on how responsible you are with your credit.

What a credit freeze won’t do

There are some other important things that freezing your credit won’t have any affect on, according to the Federal Trade Commission:

  • Freezing your credit won’t prevent you from getting your free annual credit report
  • It won’t prevent you from opening new accounts yourself, applying for a job, renting an apartment, or getting insurance. However, to do any of these things you’ll need to temporarily lift the freeze and place it again when you’re finished accessing your credit. This is all free to do.
  • Freezing a credit won’t stop criminals from accessing your existing accounts, so you’ll need to continue to keep a close eye on your statements for fraudulent activity.
  • It won’t automatically stop you from getting pre-screened credit offers. If you’d like to opt out of those, see our guide here.

Final thought

When it comes to freezing your credit, there really isn’t any downside — and it certainly won’t impact your credit score.

Even lifting the freeze when you need to access your credit and freezing it again takes mere minutes — which is certainly worth it for the peace of mind you’ll having knowing that you’re protected from criminals who could ruin your financial life.

More stories you might enjoy from Clark.com:

What is long-term care insurance and do you need it?

Long-term care insurance is an important part of financial planning that’s too often overlooked as you’re getting ready for the future.

Part of that is because there’s confusion about what long-term care insurance does. And then there’s also the question of cost, which has been unmanageable for some.

In this article, we’ll take a look at what long-term care insurance is and suggest some ways to make it more affordable.

Understanding long-term care insurance

When you’re planning for retirement, it’s important to save money to replace your income when you no longer work. But what about health care? If you have health care retiree benefits through work, that’s one option.

For those who don’t, there’s Medicare. And for those below a certain income level, there’s Medicaid.

But as you age, what happens when you need help with the everyday activities that you used to be able to accomplish on your own?

“People think the government is going to pay. But the government requires that you completely impoverish yourself before they’ll pay through the Medicaid program,” money expert Clark Howard notes. “You can have no assets and they ultimately take your family home. Ultimately, they take everything if you depend on the government.”

So it’s your choice: Take your chance that you’ll be in the small minority of seniors who never needs long-term medical care in old age. Or buy a long-term care insurance (LTC) policy.

What is long-term care insurance? — Table of contents

What is LTC insurance?

Long-term care insurance LTC or LTCI application.

Long-term care insurance is an insurance policy set up to pay for long-term medical care services. These services can include personal and custodial care in a number of living arrangements and settings.

An LTC policy will pay a daily amount for services to assist policyholders with the costs of finding the help they need to accomplish routine activities they can no longer do on their own.

Advertisement

What does it cover?

LTC policies typically pay for skilled nursing care to assist policyholders with daily activities including:

  • Bathing
  • Dressing
  • Eating

The care can be delivered in a variety of settings:

  • Nursing homes
  • Assisted living facilities
  • Skilled care in your home

When is the best time to buy LTC insurance?

Because LTC insurance can be costly, you typically want to buy it in your late 50s to early 60s. By then, your children should be grown, which frees up some of your cash flow in your life. Yet you’re also young enough that you can pass medical underwriting for a policy.

So late 50s to early 60s is really the sweet spot for buying LTC insurance.

If you’re tempted to lock in a lower rate by buying a policy earlier, Clark says don’t be. Since too many companies made promises of coverage that were too generous in the past, the market for LTC insurance is going through some pain at this time.

“Right now, there’s no advantage to buying LTC insurance early because the market’s pretty messed up right now,” the money expert notes. “Give it time to get more stable.”

How do you buy LTC coverage?

Shopping for LTC insurance may be simplified by contacting an independent agent who can shop quotes from a variety of companies for you. The following companies are all good starting points:

Understanding hybrid policies

As mentioned before, one of the big problems with LTC insurance is the cost. Premiums can often be several thousand dollars a year and they often go up by leaps and bounds. But a new version of LTC coverage called a hybrid policy may offer a solution.

“The problem with long-term care policies is that the policy premiums are not guaranteed. With a hybrid policy, you buy a whole life insurance with a rider that lets you convert the death benefit into payment while you’re living to afford long-term care,” Clark says. “The advantage is that you never have to worry about premium escalation. You have preordained the total benefit of your policy.”

According to The Wall Street Journal, the target market for these hybrid policies tends to be wealthier families who don’t want the financial legacy they plan to leave their heirs eaten up by rising medical costs.

Clark’s LTC insurance shopping tips

1. Don’t buy LTC insurance if you are very wealthy or very poor. Very wealthy means having investable assets of $3 million to $4 million — not including your home. And very poor would mean qualifying for Medicaid.

Advertisement

2. Make sure the benefit adjusts over time based on inflation. Medical inflation is higher than the normal inflation rate. You should look for an inflation level somewhere as much as 3% a year — because what seems like a good benefit today will look puny in 15 or 20 years.

3. Look for a 5-year benefit with a 6-month waiting period upfront.

4. Adult kids of aging parents may want to consider paying the premiums on their parents’ policy themselves. Why? To protect their financial interest in any possible inheritance and to protect their parents against medical expenses they may face some day.

5. Finally, only consider insurance companies that have been rated A++ or A+ (by A.M. Best), which means they are of the highest financial strength. It also means that they likely won’t jack up the rates after a few years, which has been an industry-wide problem.

Here are a few options to get you started:

LTC insurance provider Financial strength and stability rating Northwestern Mutual Life A++ New York Life A++ Mass Mutual A++ Mutual of Omaha Insurance A+

Source: A.M. Best

Final thought

A lot of people shy away from buying long-term care insurance simply because they don’t understand it. But buying this policy is a key part of financial planning for your later years.

Remember, you don’t want to have to depend on the government to pay for your long-term care — unless you’re fine with impoverishing yourself and leaving nothing behind for your heirs!

More insurance stories on Clark.com

Clark Howard: Why you need to give online banks another look

Thinking about switching your bank?

You’re probably familiar with credit unions as a superior alternative to traditional big banks, but you’d be wise to give online-only banks some consideration, too.

That’s because the online banks now offer some of the highest rates across a variety of banking products.

RELATED: Lots of banks are offering free cash: Should you bite?

Internet banks give you the best bang for your buck

How many times have you gone to your local bank branch or credit union in the past year? If you’re like most people, the answer is “not many.”

The advent of Internet banking on your smartphone has reduced the need for physical branches. If you’re fully comfortable with digital banking, there are a few compelling reasons why money expert Clark Howard says you should look at moving your money to an online bank.

Advertisement

“Recently, I’ve had to rethink banking. It used to be a two-horse race between banks and credit unions,” Clark says. “But now online banks are the new low-cost place to bank.”

Clark notes the competition is really heating up in the online banking sector.

Ally and CIT deserve your attention

Ally Bank will give you a 1% bonus on any money you move over to their online banking services as part of its newly announced PayBack Promotion. You can earn up to $1,000 on a deposit of $100,000!

And if you’re somebody who likes to chase the highest interest rates, we’ve saved one of the best deals for last.

Advertisement

CIT Bank is offering 2.30% APY on its Savings Builder account. To qualify for that rate, you need to either have an account balance of $25,000 or more OR make at least one deposit of $100 or more faithfully each month that you don’t have $25K on deposit.

If you fail to make that monthly deposit, the interest rate drops down to 1.26% APY for the following month. But if you make a deposit of $100 or more before the next month is over, you’ll get back up to the higher rate.

“Online banks are where all the action is right now in banking,” Clark says. “But it’s not just savings accounts; it’s about great deals on checking, CDs and so much more, too.”

4 things to know about Hulu’s live TV streaming service

The streaming service Hulu has grown to more than 28 million U.S. subscribers by expanding its on-demand library of television shows and releasing original programming like the award-winning “The Handmaid’s Tale.”

But the company is also focused on its new live TV option, Hulu with Live TV, which is an alternative to cable and satellite.

RELATED: How to cut the cord and never pay for cable TV again

Hulu with Live TV review: What you need to know 

For $44.99 per month, Hulu’s only live TV package offers dozens of channels and access to the provider’s entire streaming library with its Limited Commercials plan that normally costs $5.99 per month.

What makes pay-TV alternatives like Hulu unique is that there’s no cable box required and no contracts — you can cancel anytime.

Hulu with Live TV is competing with Sling TV, DirecTV Now, YouTube TV and others. I’ve tested out Hulu with Live TV three times since the service launched in May 2017.

Read on for details about the Hulu with Live TV streaming experience and my personal review…

Hulu with Live TV: Table of contents 

1. What channels do you get with Hulu with Live TV?

The channel lineup is probably the most important factor when choosing a live TV streaming service. A Hulu subscription comes with more than 60 channels, though local stations will vary depending on where you live.

For example, I entered my zip code on Hulu’s website to view the available channels in Atlanta:

Live local channels

  • ABC
  • CBS
  • FOX
  • Fox Sports South
  • Fox Sports Southeast
  • NBC
  • Telemundo
  • CW

Entertainment and lifestyle channels

  • A&E
  • Animal Planet
  • Bravo
  • Discovery Channel
  • E!
  • Food Network
  • Freeform
  • FX
  • FXX
  • HGTV
  • Investigation Discovery
  • Lifetime
  • MotorTrend (the rebranded Velocity network)
  • National Geographic
  • Nat Geo Wild
  • Oxygen
  • Pop
  • Smithsonian Channel
  • SyFy
  • TBS
  • History
  • TLC
  • Travel Channel
  • TNT
  • TruTV
  • USA
  • Viceland

Sports channels 

  • Big Ten Network
  • CBS Sports Network
  • ESPN
  • ESPN Bases Loaded
  • ESPN Goal Line
  • ESPN2
  • ESPNews
  • ESPNU
  • FS1
  • FS2
  • Golf Channel
  • NBCSN
  • Olympic Channel
  • SEC Network

News channels 

  • Cheddar
  • CNBC
  • CNN
  • CNN International
  • Fox Business
  • Fox News
  • HLN
  • MSNBC

Family and kids channels

  • Boomerang
  • Cartoon Network
  • Disney Channel
  • Disney Junior
  • Disney XD
  • Universal Kids

Movie channels 

  • FXM
  • Turner Classic Movies

Add-on premium channels

  • Cinemax
  • HBO
  • Showtime

Entertainment add-on ($7.99/month)

  • Lifetime Movies
  • FYI
  • DIY
  • Cooking Channel
  • CNBC World

Español add-on ($4.99/month)

  • ESPN Deportes
  • NBC Universo
  • CNN En Español
  • History Channel En Español.

2. Does Hulu with Live TV include DVR?

Like many of its competitors, Hulu lets you record your favorite live TV shows to watch later. You get 50 hours of cloud DVR storage with the base subscription, but that doesn’t come with the ability to fast-forward through commercials.

Advertisement

If you want that feature, Hulu says you can pay an extra $9.99 per month and get 200 hours of cloud DVR storage.

Hulu does help users manage their DVR by showing the amount of storage left. You can also choose to record all future aired broadcasts (including reruns) or only new episodes.

Hulu's Cloud DVR

3. What equipment do I need to get started? 

Hulu with Live TV requires a high-speed internet connection. After you sign up, you’ll need to use a supported device like Roku Express, Amazon Fire TV Stick or Google Chromecast to stream content on your TV.

Here’s a list of the devices that Hulu supports, according to its website:

  • Android phones and tablets
  • Apple TV (4th gen or later)
  • Chromecast
  • Fire Tablets
  • Fire TV and Fire TV Stick
  • iPhones and iPads
  • LG TV (select models)
  • Mac or PC browser
  • Nintendo Switch
  • Roku and Roku Stick (select models)
  • Samsung TV (select models)
  • Xbox 360
  • Xbox One

4. Can I watch Hulu with Live TV on multiple devices at the same time? 

You’re only allowed to watch on up to two screens at a time with your Hulu subscription, but you can upgrade to unlimited screens for an extra $9.99 a month.

That allows everyone in your house to stream at the same time, plus you can watch up to three screens when you’re on the go.

You can’t access Hulu on a living room device outside of your home network, according to Hulu’s FAQ page. The live TV service is for use by a single household, so sharing a subscription is not allowed.

A few thoughts about Hulu with Live TV… 

When I talk to people about cable and satellite TV alternatives, many of them say they would like to pick and choose the channels they want instead of paying for a bundle.

But these new streaming options are still offering bundles, so finding the right mix of channels for your family is key.

Does Hulu with Live TV have the best channel lineup? That’s going to depend on your household’s TV viewing habits. I’ve put together a chart to help you see what the leading streaming services offer for around $40 to $50 a month.

Advertisement

In the meantime, here are some key takeaways from my experience testing out Hulu with Live TV…

Navigation 

I found Hulu with Live TV pretty easy to use. The clean layout makes it simple to search for live programming, record shows and movies, and access on-demand content that’s included with a subscription.

In May 2018, Hulu addressed one of its biggest flaws by adding a live TV guide to improve channel surfing.

An updated live TV guide that lets you plan two weeks of streaming went live on Hulu.com in July 2019 and is coming to more devices soon. This is something customers have been requesting from the start.

Getting around Hulu may take an extra click or two, so you need to play around with its features when you first sign up.

Hulu's TV guide feature

Personalization 

Just want to get back to your favorite show as quickly as possible? That’s one of Hulu’s strengths. From the home screen, the “Keep Watching” and “My Channels” tabs help you pick up where you left off.

In addition, you can keep track of TV shows, movies and sporting events by adding content to the “My Stuff” category.

Performance 

When Hulu with Live TV first launched in May 2017, I was disappointed. I couldn’t fully appreciate what it had to offer because of frequent buffering and error messages.

After I posted my initial article about Hulu, some of Clark.com’s readers said they also had the same performance issues.

However, I’ve had very little buffering during my third time around with Hulu from August to October 2018, so it may be worth giving the service another chance if you had trouble before.

Advertisement

Hulu recommends an internet download speed of 8 Mbps for the live TV service. See our guide to test your download speed.

Pricing and add-ons 

Hulu with Live TV starts with a free 7-day trial to give you time to see if the service is a good fit.

The $44.99 monthly price is a great value if you take advantage of Hulu’s entire streaming library, but add-ons for enhanced DVR, unlimited screens and premium channels can quickly increase your bill.

For example, if you want live TV and access to Hulu’s on-demand library with no commercials, that’s $50.99 per month.

Hulu with Live TV: Pros and cons

Pros  Cons One simple plan for $45/month Expensive add-ons Hulu’s on-demand streaming library included Must upgrade DVR to fast-forward through commercials 50 hours of cloud DVR storage Only two screens at once

Final thought 

If Hulu’s channel lineup has everything you need, take Hulu up on its free trial offer. There’s no contract or long-term commitment. You can always cancel and try other streaming services until you find a keeper.

Read more and compare your options in Clark’s guide to the best live TV streaming plans and deals!